Leave a Message

Thank you for your message. We will be in touch with you shortly.

Explore Our Properties
Essential Market Intel

The Ultimate Guide to Buying a Condo on 30A

Complete Buyer Guide

Everything You Should Know Before Purchasing a Beachfront or Resort Condo Along Scenic Highway 30A

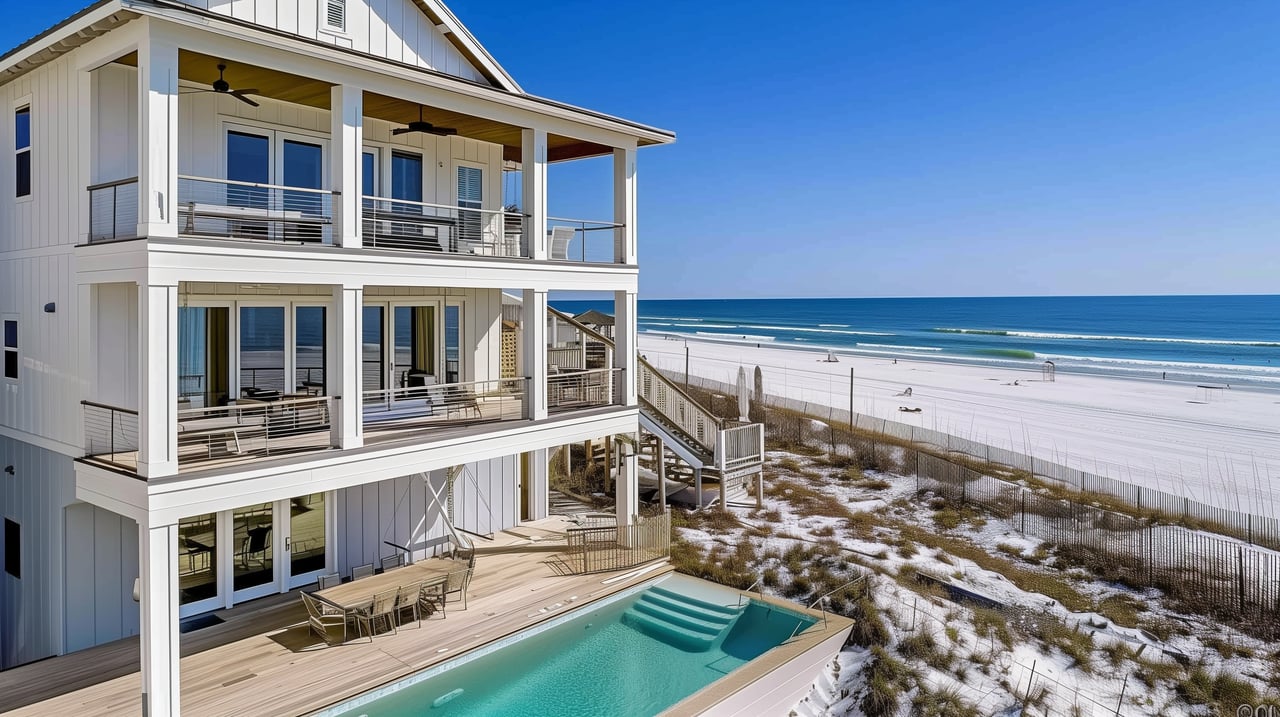
This guide explains everything buyers should know before purchasing a condominium on Florida’s Scenic Highway 30A, including HOA fees, insurance, special assessments, reserve funding, vacation rental rules, beach access, maintenance responsibilities, ownership costs, and how condos compare to townhomes and single-family homes. Written by local 30A real estate experts, it’s designed to help buyers make informed decisions with confidence.

Default Image

Lifestyle Comparison

Is Buying a Condo on 30A Worth It?

For many buyers, absolutely.

Condominiums offer one of the easiest ways to own property at the beach while minimizing the maintenance that comes with a single-family home.

Many owners appreciate the ability to lock the door, leave for weeks or months at a time, and know that the property is still being cared for.

A condo may be the right choice if you value:

Walkability to the beach
Lower exterior maintenance
Resort-style amenities
Pools and fitness centers
Vacation rental potential
Simplified ownership
Security
Professional property management

A single-family home may be a better fit if you value:

Complete privacy
Large outdoor living spaces
Private pools
Greater flexibility for renovations
Fewer community rules
More storage and parking

Neither option is better—they simply offer different lifestyles.

Common Misconceptions

What Do You Actually Own?

Default Image

One of the biggest misconceptions about condominium ownership is understanding what you’re purchasing.

Generally speaking, when you purchase a condo, you own everything from the interior walls inward.

That typically includes:

Flooring

Plumbing fixtures

Drywall finishes

Electrical fixtures

Cabinets

Paint

Interior doors

Interior trim

Appliances

HVAC equipment serving your unit (in many communities)

Default Image

The condominium association generally maintains the common elements, including:

Roof

Pools

Building structure

Parking areas

Exterior walls

Beach walkovers

Elevators

Exterior lighting

Hallways

Shared plumbing systems

Landscaping

Shared electrical infrastructure

Every condominium declaration is different, so your REALTOR® should review exactly where the association’s responsibilities begin and end before closing.

Dues Decoded

What Do HOA Dues Cover?

This is one of the most common questions buyers ask.

The answer depends on the community, but HOA dues often include many expenses that homeowners would otherwise pay separately.

Depending on the association, monthly dues may include:

Exterior Building Insurance
Roof Maintenance and Replacement
Landscaping
Lawn Care
Pool Maintenance
Fitness Center Maintenance
Building Maintenance

Elevator Service
Exterior Painting
Pest Control
Water
Sewer
Trash Service
Cable Television
Internet

Security Professional Management
Accounting
Reserve Funding for Future Repairs
Common-Area Electricity
Beach Walkovers
Private Beach Maintenance
where Applicable

Some communities include more. Others include less.

One important point to remember is that higher HOA dues do not necessarily mean a property is more expensive to own. In many cases, higher dues reflect stronger reserve funding, better maintenance, more amenities, or more comprehensive insurance coverage.

Default Image

Evaluating Expenses

Why Are Some HOA Fees So Much Higher?

There are several reasons.

A luxury beachfront building with elevators, underground parking, multiple pools, fitness facilities, concierge services, and private beach amenities naturally costs more to maintain than a smaller building with minimal common areas.

Factors that commonly affect HOA dues include:

Age of the building
Insurance costs
Elevators
Beachfront exposure
Number of amenities
Staffing
Reserve contributions
Deferred maintenance
Construction costs
Storm exposure
Size of the association

Rather than comparing HOA dues alone, buyers should evaluate what those dues actually provide.

Default Image

Protection Basics

Understanding Condo Insurance

One of the advantages of condominium ownership is that the association typically carries a master insurance policy covering much of the building itself.

As an owner, you’ll usually purchase an individual HO-6 condominium insurance policy.

An HO-6 policy often provides coverage for:

Interior finishes
Personal belongings
Cabinets
Flooring
Appliances
Liability protection
Additional living expenses after certain losses
Improvements you’ve made to the unit

Many owners also choose to carry Loss Assessment Coverage, which can help protect against certain special assessments resulting from covered insurance claims.

Because every association’s master policy is different, buyers should always review both the association’s insurance coverage and their personal insurance needs before closing.

Default Image

Financial Protection

What Are Special Assessments?

A special assessment is an additional charge levied by a condominium association to cover expenses not fully funded through the regular operating budget or reserve accounts.

Assessments may be necessary for:

Roof replacement
Elevator modernization
Structural repairs
Concrete restoration
Exterior painting
Hurricane damage
Major plumbing projects
Unexpected insurance costs

Not every condominium experiences special assessments.

Well-managed associations that consistently fund reserves often reduce the likelihood of large unexpected assessments, although no building is completely immune from unforeseen repairs.

Cost Drivers & Legislation

Rising Fees and Florida’s Condo Laws Explained

Default Image

Why Have Florida Condo Fees Increased?

Many buyers have noticed higher HOA dues across Florida in recent years.

Several factors have contributed to these increases, including:

  • Rising insurance premiums
  • Higher construction costs
  • Inflation
  • New reserve funding requirements
  • Structural inspections for certain buildings
  • Increased labor costs
  • Deferred maintenance from prior years

While these changes have increased monthly expenses in many communities, they are also helping associations better prepare for future repairs and maintain safer buildings.

Default Image

Florida’s New Condo Reserve Laws

Following the tragic Surfside condominium collapse in 2021, Florida enacted new legislation requiring many condominium associations to perform structural inspections and more fully fund reserves for major building components.

These requirements have resulted in increased transparency for buyers while encouraging associations to plan more proactively for long-term maintenance.

When purchasing a condominium, buyers should review:

  • Reserve studies
  • Structural inspection reports (when applicable)
  • Annual budgets
  • Financial statements
  • Meeting minutes
  • Current reserve balances

These documents often provide valuable insight into the financial health of the community.

Know Before You Buy

Key Considerations Beyond the Unit

Usually, yes—but there are limits.

Most associations allow owners to renovate interior finishes, including:

  • Kitchens
  • Bathrooms
  • Flooring
  • Paint
  • Lighting
  • Cabinets
  • Countertops

Exterior modifications are typically much more restricted.

Items such as windows, doors, balconies, exterior colors, and structural changes often require approval from the association or may not be permitted at all.

Always review the association’s governing documents before planning renovations.

One of the reasons buyers are drawn to 30A condominiums is the potential to generate rental income.

However, every condominium has its own rental policies.

Questions buyers should ask include:

  • Are short-term rentals allowed?
  • Is there a minimum rental period?
  • Are there rental management requirements?
  • Are owner stays restricted?
  • Are pets allowed?
  • Are golf carts permitted?
  • Are there occupancy limits?

Understanding these rules before purchasing can prevent future surprises.

Not all beach access is created equal.

Depending on the community, owners may enjoy:

  • Private deeded beach access
  • Dedicated neighborhood access
  • Public beach access
  • Beach tram service
  • Beach chair service
  • Gulf-front walkovers

One of the most important aspects of evaluating any condominium is understanding exactly what type of beach access accompanies ownership.

Parking arrangements vary widely among condominium communities.

A property may include:

  • Assigned parking
  • Covered parking
  • Parking garages
  • Owner storage closets
  • Climate-controlled storage
  • Bike storage
  • Paddleboard storage
  • EV charging stations

These features can significantly impact both convenience and resale value.

Essential Questions

Questions Every Condo Buyer Should Ask

Before making an offer, ask your real estate professional to help you review:

How much money is in reserves?

Are there any upcoming special assessments?

Are there pending lawsuits?

What does the HOA fee include?

What insurance does the association carry?

Are there rental restrictions?

What are the pet policies?

Are there parking restrictions?

Are there storage units?

What amenities are included?

Has the building experienced recent storm damage?

What major repairs are expected over the next five to ten years?

These questions often reveal far more about a condominium than the listing itself.

Default Image

Buyer Watchouts

Common Mistakes Buyers Make

The biggest mistake is focusing only on the monthly HOA dues.

Instead, buyers should evaluate the complete ownership experience, including maintenance history, reserve funding, insurance coverage, amenities, rental policies, and long-term building health.

A lower HOA fee isn’t always a better value if the building has underfunded reserves or deferred maintenance.

Likewise, a higher HOA fee may provide peace of mind through stronger financial planning and more comprehensive services.

Default Image

Finding Your Match

Should You Buy a Condo, Townhome, or Single-Family Home?

There isn’t a universal answer.

It depends on how you plan to use the property.

If your goal is easy ownership with minimal maintenance, a condominium may be an excellent fit.

If privacy, outdoor living space, and complete control over your property are priorities, a single-family home may better match your lifestyle.

Townhomes often provide a balance between the two.

Choosing the right property starts with understanding your long-term goals—not simply comparing prices.

Default Image

The Live30A Advantage

How Live 30A Helps Buyers

Purchasing a condominium involves much more than finding the right floor plan or Gulf view.

Before our clients purchase a condo, we help them review:

HOA budgets
Reserve funding
Meeting minutes
Insurance summaries
Rental restrictions
Upcoming projects
Special assessment history
Comparable sales
Rental performance when applicable
Long-term ownership costs

Not every condominium experiences special assessments.

Well-managed associations that consistently fund reserves often reduce the likelihood of large unexpected assessments, although no building is completely immune from unforeseen repairs.

Common 30A Condo Buyer Questions & Answers

Most HOA dues cover exterior building insurance, roof maintenance, landscaping, pools, common-area maintenance, reserve funding, and professional management. Some communities also include water, sewer, internet, cable, fitness centers, or private beach amenities. Coverage varies by association.

Often, yes. HOA dues typically cover many expenses homeowners would otherwise pay separately, including exterior maintenance, insurance, landscaping, and amenities. Focus on the overall value—not just the monthly fee.

Not necessarily. Condos usually have higher monthly HOA dues but often lower maintenance responsibilities. The total cost depends on the property, amenities, insurance, and your lifestyle.

Most owners purchase an HO-6 condo insurance policy to protect their belongings, interior finishes, liability, and improvements. The condominium association generally insures the building itself.

No. The HOA typically insures the building and common areas, while owners are responsible for personal belongings, interior finishes, liability, and certain improvements.

A special assessment is an additional charge used to fund major repairs or unexpected expenses that aren’t fully covered by the association’s operating budget or reserves.

Review the reserve funds, annual budget, financial statements, meeting minutes, insurance coverage, and any planned capital improvements. A healthy association is proactive, transparent, and well maintained.

Insurance costs, inflation, construction expenses, and Florida’s updated reserve funding requirements have contributed to higher HOA dues across many communities.

It depends on the association. Some allow nightly rentals, while others require weekly or monthly minimum stays—or prohibit short-term rentals altogether.

Possibly. Each condominium has its own rental rules, so always verify the association’s policies before purchasing if vacation rentals are important to you.

They can be. The best-performing condos combine strong locations, desirable amenities, reasonable ownership costs, and rental-friendly policies. Every property should be evaluated individually.

Usually, yes. Most owners can renovate the interior of their unit, but exterior changes and structural modifications often require HOA approval.

In most cases, yes. Interior paint and cosmetic updates are generally allowed, though exterior changes are typically regulated by the HOA.

The HOA usually maintains the roof, but responsibility for interior damage depends on the association documents and insurance policies.

In many condominiums, the HVAC system serving your individual unit is the owner’s responsibility. Some buildings have centralized systems maintained by the association.

The HOA typically manages repairs to the building through its master insurance policy, while owners rely on their own insurance for personal property and certain interior damages.

Every association has different pet policies regarding size, breed, quantity, and rental guests. Always review the rules before buying.

Many do, but not all. Beach access may be private, deeded, neighborhood-only, or public. Understanding exactly what comes with a property is an important part of the buying process.

Parking varies by community and may include assigned spaces, garages, covered parking, guest parking, golf cart parking, or owner storage.

At a minimum, review the HOA budget, financial statements, reserve information, meeting minutes, insurance summary, governing documents, and any pending special assessments.

Ask about reserves, HOA dues, insurance, rental restrictions, beach access, pet policies, parking, upcoming assessments, and expected major repairs.

We help buyers look beyond the listing by reviewing the association’s finances, insurance, rental rules, reserves, meeting minutes, and long-term ownership costs so they can make informed decisions with confidence.

Our goal is to help you understand not only what you’re buying—but how it will feel to own it for years to come. If you’re considering purchasing a condo anywhere along Scenic Highway 30A, we’d be honored to help you evaluate your options and guide you through the process with confidence.

Follow Us On Instagram